For many Malaysians, opening a bank account is one of the first steps toward financial independence. Whether you are a student managing your first allowance, a salaried employee receiving monthly income, or a small business owner handling daily transactions, the type of account you choose shapes how you interact with your money. Yet despite their everyday use, current accounts and savings accounts are often confused. Many assume they are interchangeable. In reality, they serve fundamentally different purposes.
Understanding these differences is not just about banking terms. It is about making choices that align with your financial life in Malaysia—whether you are saving for a goal, running a business, or simply trying to manage your money more effectively.
What Is a Savings Account
A savings account is designed primarily for storing money safely while earning a modest return over time. It is the most common type of account opened by individuals who do not run a business. The focus is on security, simplicity, and gradual growth.
Most savings accounts in Malaysia require minimal documentation. You typically need only your MyKad and a small initial deposit, sometimes as low as RM1. This makes it accessible to students, homemakers, freelancers, and others who may not have large sums to start with. Once opened, the account earns interest on the balance held, though the rate varies depending on the bank and product type.
Basic savings accounts usually offer interest rates around 0.2% per annum. While this may seem small, it is still better than keeping cash at home. More advanced savings products, such as digital-only accounts or those linked to salary crediting, can offer higher tiered interest rates for maintaining certain balances or meeting specific conditions.
One important feature of savings accounts is the limitation on transaction frequency. Most banks allow only a few free withdrawals or interbank transfers per month. Exceeding this limit often results in service charges. This design reinforces the idea that a savings account is not meant for daily spending but for preserving capital. Additionally, savings accounts do not come with cheque books. Payments must be made through debit cards, online transfers, or over-the-counter withdrawals.
This structure makes savings accounts ideal for building an emergency fund, saving for short-term goals like a phone upgrade or a trip, or simply keeping extra income secure. For many Malaysians operating in cash-based economies, a savings account is also the first step into the formal financial system, providing a record of financial activity that can support future credit applications.
What Is a Current Account
A current account is built for activity, not accumulation. It is primarily used by businesses, sole proprietors, and professionals who need to manage frequent financial transactions. While individuals can open current accounts, they are most valuable for those who require flexibility in payments, receipts, and operational cash flow.
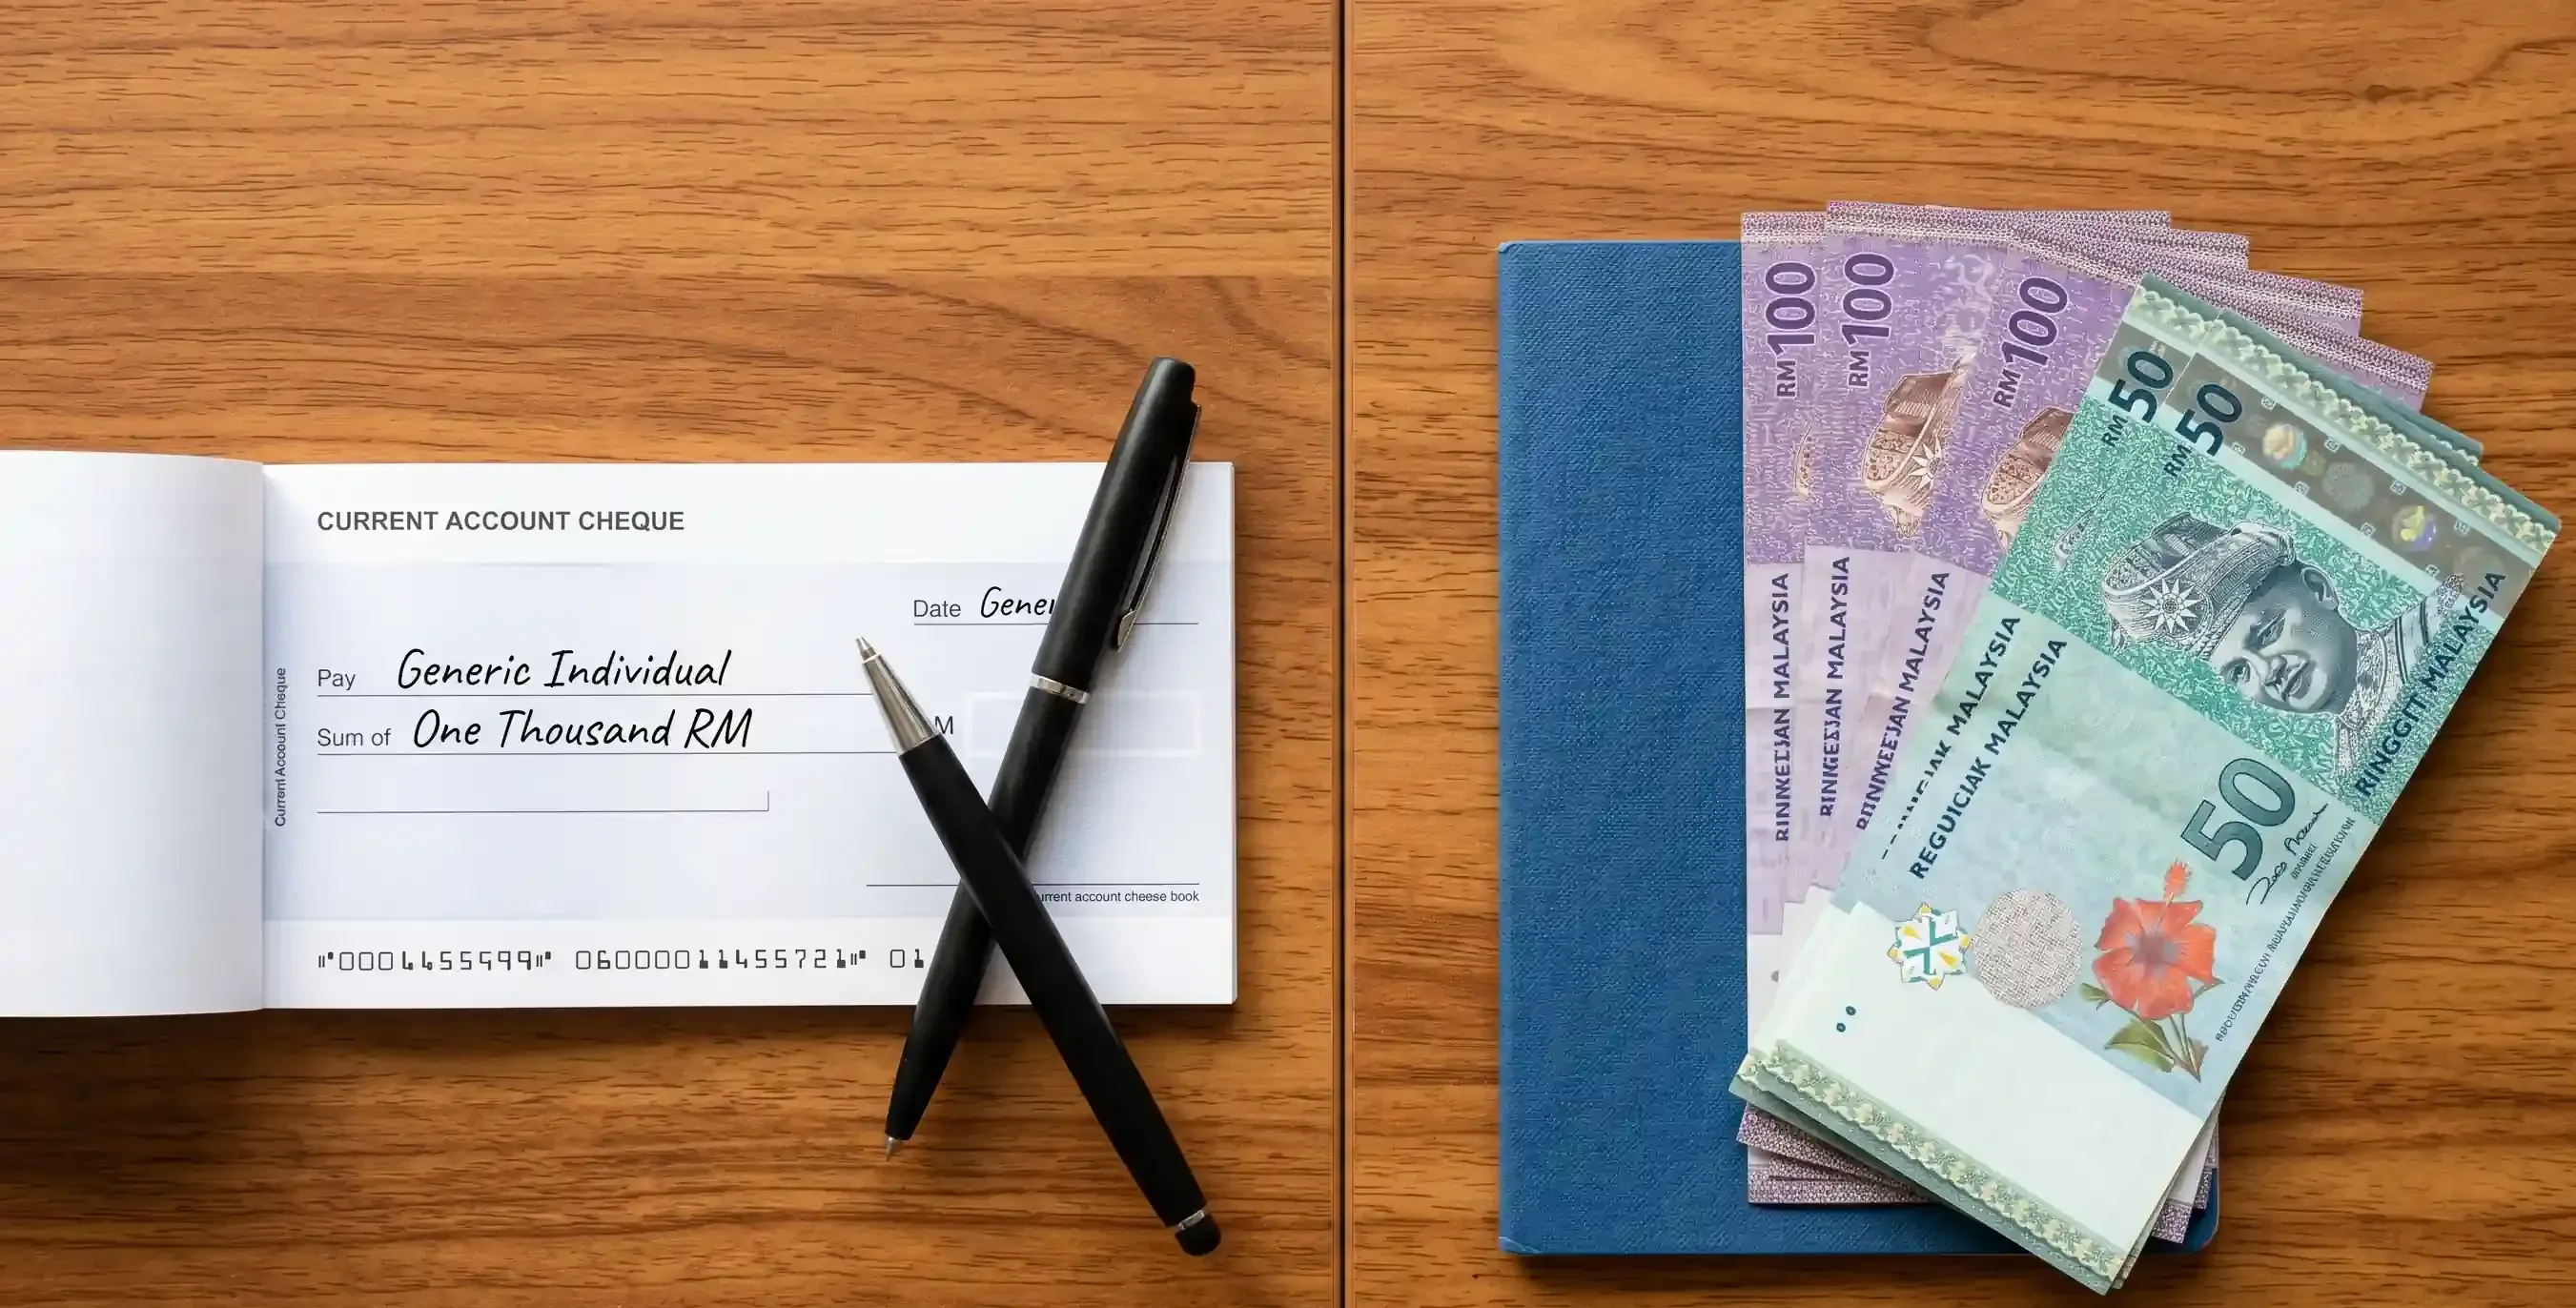
The defining feature of a current account is the ability to issue cheques. This is essential in many business contexts, such as paying suppliers, settling rental agreements, or making formal deposits. When a business opens a current account, it registers authorised signatories with the bank. Any change in personnel must be reported immediately to maintain security and compliance.
Current accounts generally do not pay interest, or if they do, it is only on very high balances, often above RM100,000. This reflects their purpose: they are not meant for saving but for liquidity. The money in a current account is expected to move in and out frequently to support daily operations.
Another key difference is the minimum balance requirement. While savings accounts may allow balances as low as RM20, current accounts often require an initial deposit of five hundred ringgit or more and mandate a higher average monthly balance to avoid service fees. This reflects the greater administrative cost of managing active business accounts.
Current accounts also typically allow unlimited transactions without additional charges. There are no monthly caps on transfers, withdrawals, or payments. This unrestricted access is critical for businesses that process numerous transactions each month and cannot afford delays or penalties.
Many current accounts also offer an overdraft facility, subject to approval. This allows the account holder to withdraw more than the available balance up to a pre-approved limit. While overdrafts come with interest and fees, they provide a safety net during periods of uneven cash flow, such as when waiting for client payments while still needing to cover expenses.
How the Two Accounts Serve Different Needs
The core difference lies in purpose. A savings account encourages you to keep money aside and grow it slowly. A current account enables you to move money quickly and efficiently.
A salaried employee saving for a car or a wedding will benefit far more from a high-interest savings account than from a current account with no returns and higher fees. Conversely, a food truck operator in Johor Bahru who pays weekly suppliers and collects daily cash sales needs the transactional freedom and cheque capability of a current account.
This distinction is not about which account is better. It is about which one fits your current financial reality. Confusing the two can lead to unnecessary costs. For example, using a savings account for frequent business transactions may result in monthly fees. Using a current account to store long-term savings means missing out on potential interest earnings.
Why Many People Use Both Accounts
There is no rule that limits you to one account. In fact, many financially aware Malaysians hold both a savings account and a current account simultaneously.
They use the savings account to build emergency reserves, save for specific goals, or park surplus income. They use the current account to manage business operations, pay bills, or handle regular high-volume transactions. This separation brings clarity to financial management. It becomes easier to track business income versus personal spending, prepare for tax obligations, and avoid accidentally depleting savings through routine expenditures.
For sole proprietors or freelancers, this dual approach is especially valuable. It creates a clear boundary between personal and professional finances, which is important for record-keeping, accountability, and future loan applications.
How to Choose the Right Account for You
Start by asking yourself how you actually use your money. Do you make more than five withdrawals or transfers each month? If so, a savings account may charge you extra fees, while a current account will not.
Do you need to issue payments to third parties using formal instruments? Only a current account provides cheque facilities. Are you trying to grow your money over time? Then a savings account with competitive interest rates is more suitable.
Also consider your income pattern. If you receive irregular payments—as many freelancers and gig workers do—a current account with an overdraft option might offer needed flexibility. If you have a steady salary and consistent expenses, a savings account can help you automate saving and build discipline.
Always review the full terms before opening an account. Look beyond promotional headlines. Check the minimum balance requirements, monthly maintenance fees, transaction limits, and interest calculation methods. Some accounts appear attractive at first glance but come with hidden costs that add up over time.
The Role of Banking in Your Financial Identity
Your choice of account is more than a practical decision. It reflects your financial identity in Malaysia’s modern economy. A savings account signals intentionality and long-term thinking. A current account signals activity and operational readiness.
Both are valid. Both are protected under Perbadanan Insurans Deposit Malaysia. Neither is a sign of financial weakness or strength. What matters is alignment—choosing the tool that supports your actual behaviour, not an idealised version of it.
In a country where financial inclusion is expanding but literacy gaps remain, understanding these basics is a form of empowerment. It allows you to avoid unnecessary fees, maximise returns, and position yourself for greater control over your money.
Taking the Next Step with Clarity
Before you open your next account, pause and reflect on your real financial habits. The right account should simplify your life, not complicate it. It should support your goals, whether that is launching a business, saving for education, or simply gaining peace of mind.
You do not need to be a finance expert. You just need to understand the purpose of each account and match it to your needs. That simple act of awareness can save you money, reduce stress, and put you on a stronger financial path in Malaysia.
Legal Notice
The contents of this publication are for reference purposes only and may not be current as at the date of accessing this publication. We do not take responsibility for the accuracy of its contents. They do not constitute legal advice and should not be relied upon as such. Specific legal advice about your specific circumstances should always be sought separately before taking any action based on this publication.