Debt Service Ratio (DSR) is a central component of loan assessments in Malaysia, as it helps financial institutions determine whether a borrower can manage additional repayment obligations. When applicants request financing for a home, a vehicle, or a personal loan, banks review the stability of their income, the structure of existing commitments, and the nature of their employment. These factors allow lenders to form an objective view of repayment capacity and ensure that new obligations do not create financial pressure that could disrupt essential monthly spending.
By applying DSR as a formal evaluation tool, Malaysian banks maintain a consistent approach to responsible lending. The ratio offers a detailed comparison between income and outstanding commitments, helping institutions measure financial resilience and identify suitable loan amounts. This introduction establishes the foundation for understanding how DSR aligns with overall credit assessment procedures and why it directly influences the outcome of every loan application.
What Is the Debt Service Ratio (DSR)? Core Definition and Purpose
Malaysian banks integrate DSR into the loan evaluation workflow to determine whether an applicant meets internal lending thresholds. Each institution establishes its own acceptable DSR bands, which vary according to the borrower’s income group, employment stability, and perceived risk level.
Applicants with higher and more predictable earnings may qualify for broader limits, while those with fluctuating or entry-level income may be assessed under stricter parameters. These differences reflect the bank’s efforts to balance lending opportunities with responsible credit management.
When processing a loan application, banks review supporting documents, compute the applicant’s DSR, and compare the result against their internal risk model. Institutions may apply different formulas, include or exclude certain commitments, or assess variable expenses differently.
As a result, two banks may produce slight variations in the applicant’s DSR even when using the same financial data. The metric influences both preliminary assessments and the final approval stage, shaping the bank’s decision to approve, adjust, or decline the requested loan amount.
How DSR Is Calculated: Formula, Components, Examples
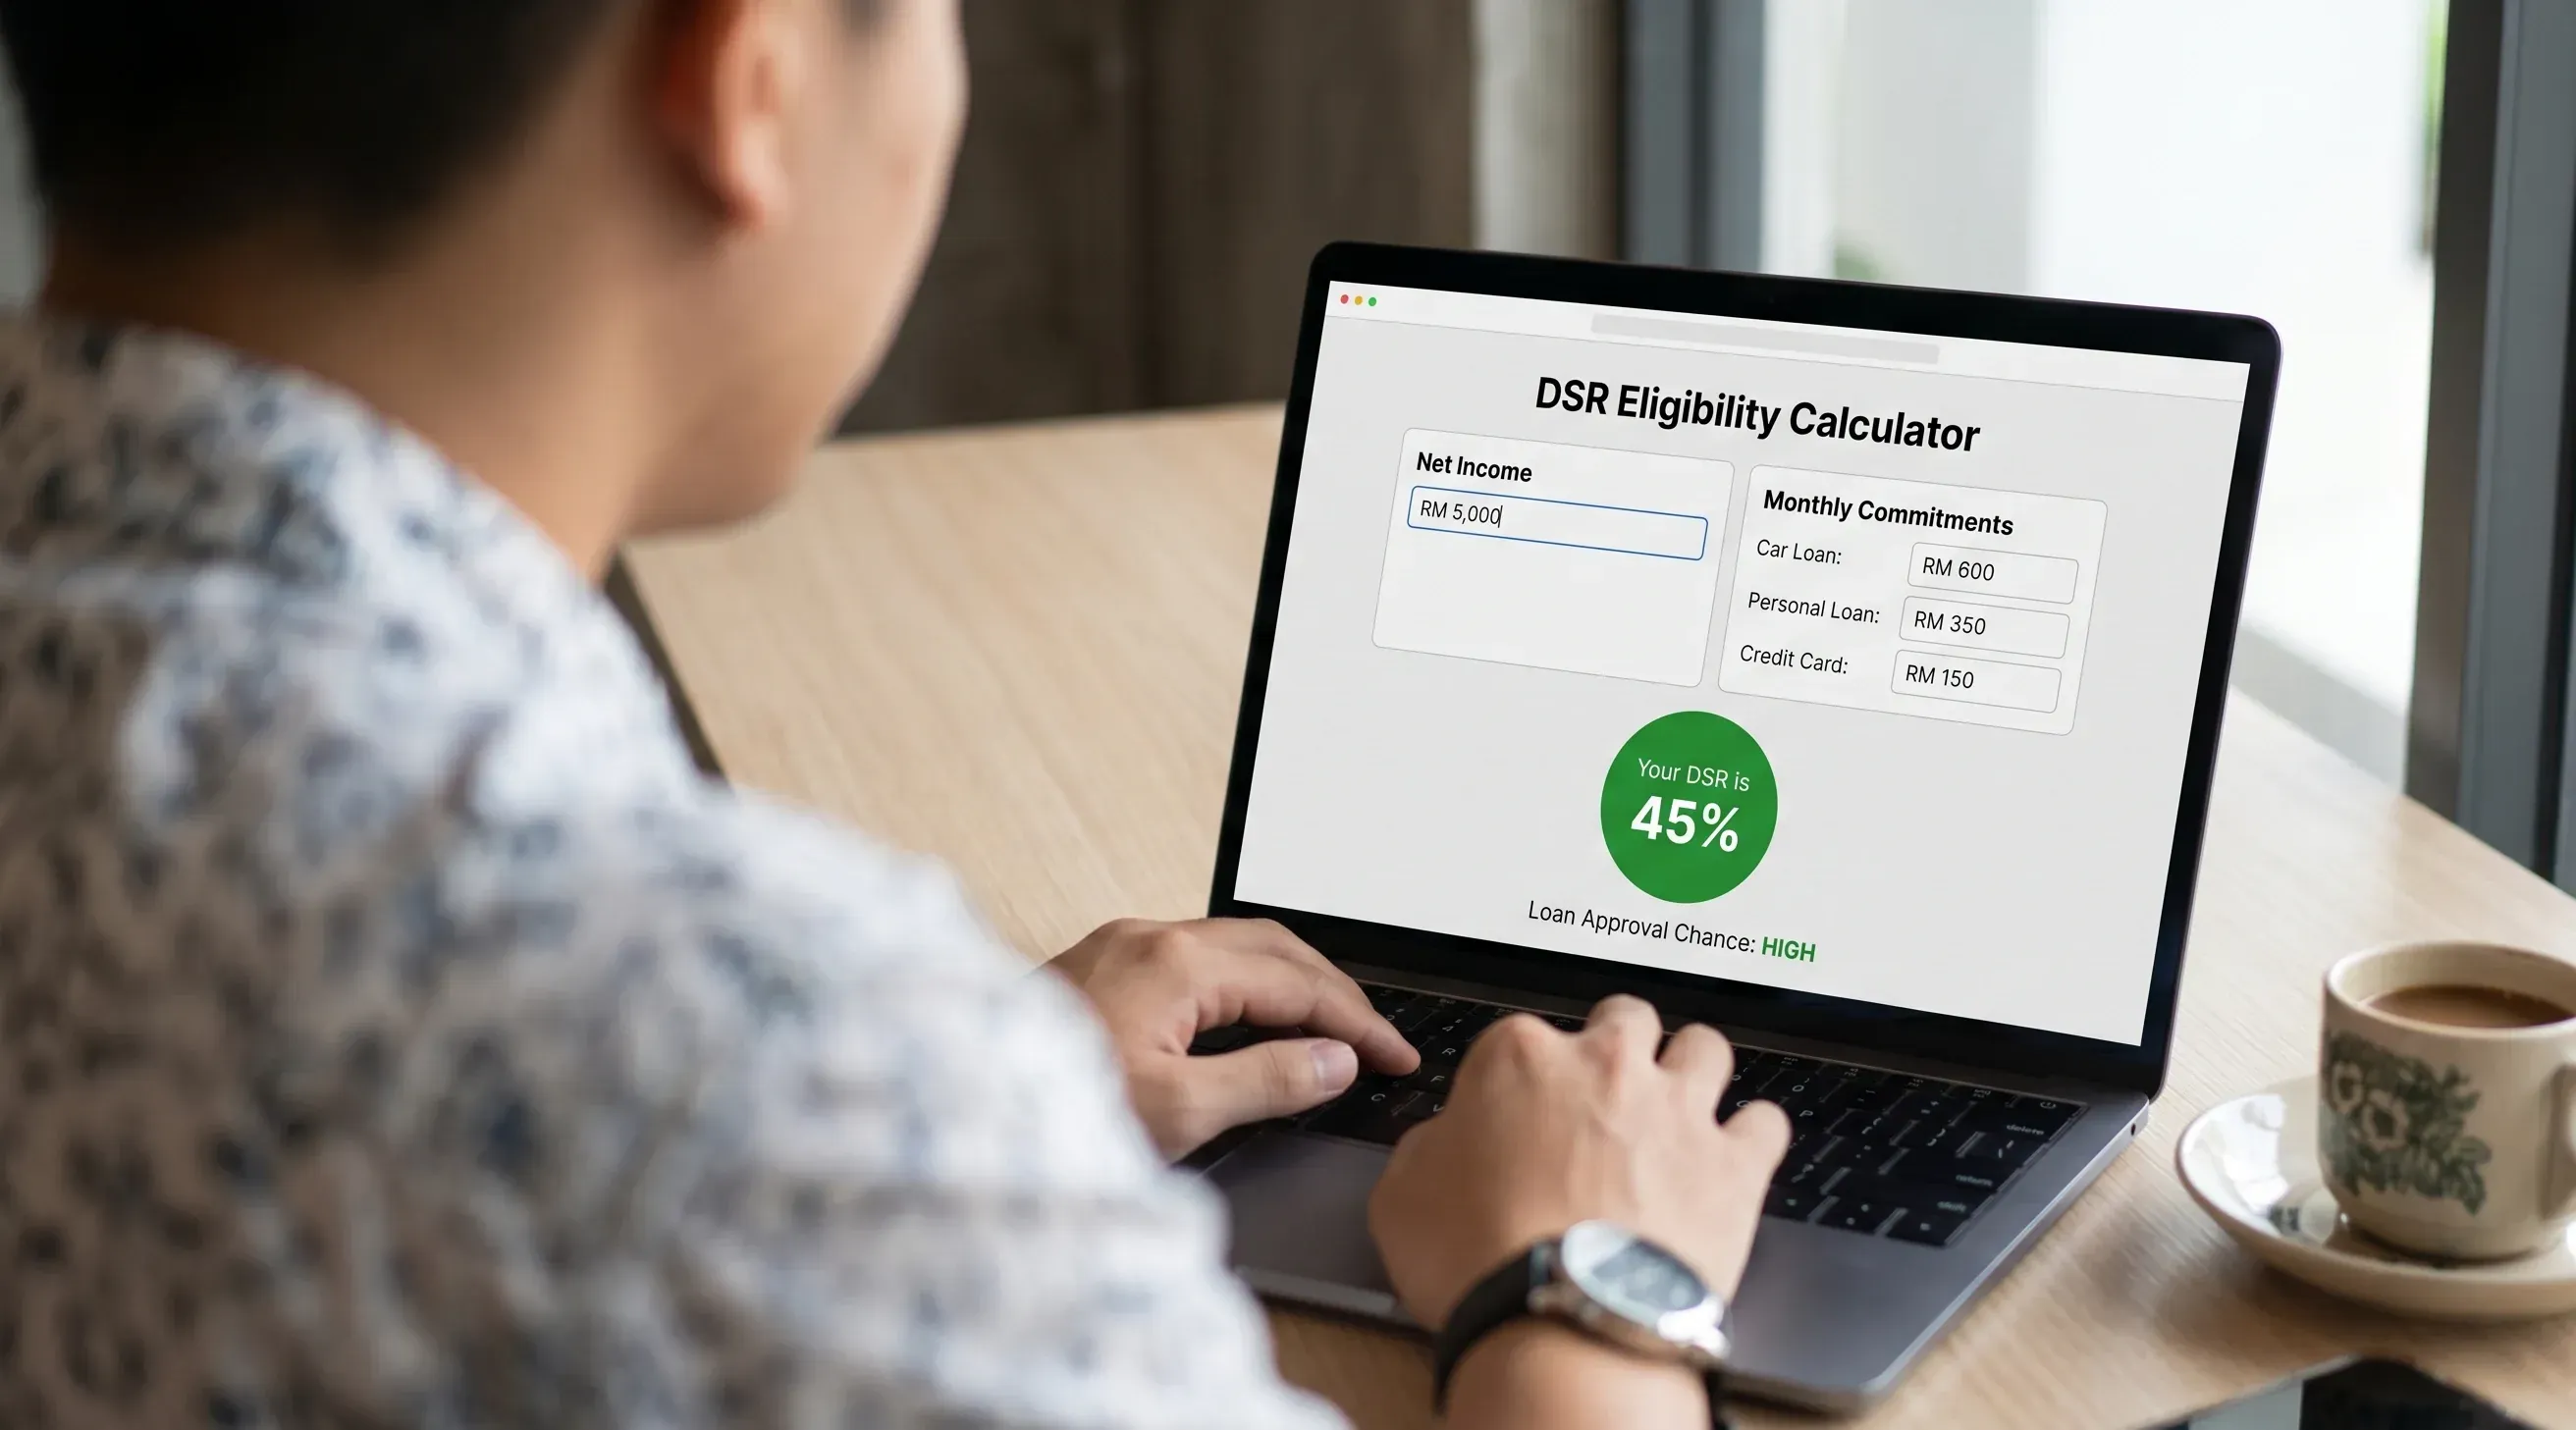
The standard DSR formula compares total monthly debt commitments with the borrower’s net income. At its core, the calculation looks like this:
DSR = (Total Monthly Debt Commitments ÷ Net Monthly Income) × 100
To understand the formula, it is important to break down the elements included in each part. Net income refers to documented income after statutory deductions such as EPF and SOCSO.
Debt commitments generally include car loan installments, PTPTN payments, personal loan installments, housing loan installments, and credit card minimum payments. Some banks also consider non-bank obligations, such as cooperative loans or financing from licensed lenders, depending on their internal policy.
Below is a simple illustration that demonstrates how the calculation works:
| Component | Amount (RM) |
|---|---|
| Net Monthly Income | 4,500 |
| Car Loan Installment | 500 |
| Personal Loan Installment | 350 |
| Credit Card Minimum Payment | 150 |
| Total Commitments | 1,000 |
DSR = (1,000 ÷ 4,500) × 100 = 22.22%
Differences in results occur because each bank may adjust how it treats certain obligations, include additional commitments, or interpret income stability differently. These variations lead to different DSR outcomes even when evaluating the same applicant.
Where Borrowers Can Access Their Financial Commitments for DSR Review
Borrowers preparing for a loan application can review their financial obligations by referring to several reliable sources. The most comprehensive option is CCRIS, which compiles information on outstanding loans, repayment behaviour, and credit limits from banks across Malaysia.
This report allows applicants to verify their total commitments and identify entries that affect their DSR. In addition to CCRIS, borrowers can use bank statements to track monthly deductions, loan installments, and recurring payments that form part of their financial obligations.
Those who manage additional financing outside traditional banks may rely on personal financial spreadsheets or statements from relevant lenders to ensure accurate reporting. Independent reporting services also provide structured summaries of commitments, helping borrowers confirm that all data used in DSR calculations is complete. Preparing these documents before applying for a loan helps create a realistic view of affordability and supports a smoother evaluation process.
Key Factors That Influence Your DSR in Malaysia
Multiple components shape the final DSR value, and understanding these variables helps borrowers interpret how lenders evaluate repayment capacity. Banks review income patterns, outstanding commitments, and credit behaviour to determine whether the applicant meets internal risk thresholds.
Employment type and stability of income form the foundation of this assessment, as predictable earnings support a more favourable interpretation of repayment potential. Credit history also plays a role, especially when reports include missed installments or irregular repayment records.
Below is a structured list detailing the primary factors influencing DSR in Malaysia:
- Employment Type — Salaried employees with formal documentation provide clearer income verification compared to individuals with variable or commission-based earnings.
- Income Stability — Consistent monthly income supports a more reliable DSR calculation. Variability in earnings may result in stricter evaluation.
- Credit History — Records of past repayments, including punctual or late payments, shape how banks interpret financial reliability.
- Number of Active Loans — Each loan increases total commitments, raising the percentage of income allocated to debt servicing.
- Credit Card Minimum Payments — Higher limits or outstanding balances increase mandatory minimum payments that affect DSR.
- Past Delinquencies — Missed or overdue payments influence the bank’s confidence in repayment behaviour.
- Lack of Credit History — Limited credit activity provides fewer data points for assessment, which may affect the final interpretation.
Since these criteria evolve as financial circumstances change, DSR remains a dynamic indicator that reflects a borrower’s current financial position.
Practical Ways to Improve Your DSR Before Applying for a Loan
Improving DSR requires a structured approach that focuses on reducing commitments and strengthening documented income. Borrowers preparing for a loan application can begin by reassessing current financial responsibilities to identify obligations that can be settled or restructured.
This creates additional financial space and improves the ratio used by banks during evaluations. Another important aspect involves ensuring that all income sources are properly documented so lenders can include them in their assessment. Clear records support a more accurate interpretation of repayment capacity.
Below is a list of practical strategies that help improve DSR in Malaysia:
- Settle High-Interest Debts — Clearing expensive commitments reduces monthly obligations and lowers the DSR percentage.
- Consider Debt Consolidation — Combining several loans into one installment can streamline repayments and reduce total monthly commitments.
- Optimise Monthly Expenses — Reviewing recurring costs helps direct more income toward essential obligations, including existing debts.
- Increase Documented Income — Providing verifiable proof of additional earnings strengthens overall affordability.
- Correct Credit History Issues — Addressing unresolved entries or clarifying outdated records helps improve the lender’s assessment.
- Reduce Credit Card Balances — Lowering outstanding amounts decreases minimum monthly payments included in the DSR calculation
These measures help borrowers strengthen their financial position before submitting a formal loan application.
DSR vs. Affordability: Why Eligibility Doesn’t Always Mean You Can Afford a Loan
While DSR plays an important role in determining loan eligibility, it does not fully reflect the borrower’s day-to-day financial capacity. Banks use DSR to confirm that repayment obligations fit within a predetermined percentage of income, but the metric does not consider all personal expenses.
Borrowers may qualify for a loan based on DSR yet face difficulties if monthly obligations leave limited funds for essential spending. Understanding the difference between technical eligibility and practical affordability helps applicants make responsible financial decisions.
Additional expenses form part of real household budgeting and influence the borrower’s long-term comfort. These include general living costs, utility bills, transportation needs, and unexpected financial obligations.
For housing loans, upfront and ongoing charges such as stamp duty, legal fees, and the down payment create additional financial pressure. Because DSR does not reflect these external factors, borrowers must conduct their own affordability assessment alongside the bank’s evaluation to ensure a balanced and sustainable financial outcome.
What to Do if Your Loan Application Is Rejected Due to DSR
A rejection based on DSR indicates that the lender considers the current financial structure too heavy for an additional commitment. Borrowers can begin by recalculating their DSR using accurate income and commitment data to identify which elements contributed to the outcome.
Reviewing the bank’s assessment helps determine whether the rejection was caused by high monthly debts, insufficient documented income, or an internal DSR limit that the applicant exceeded. This analysis forms the basis for planning the next steps.
Once the underlying issue is identified, several actions can help improve the likelihood of future approval. Borrowers may consider applying to a bank with a different DSR threshold, correcting documentation errors, or reducing existing commitments before reapplying.
Another option includes restructuring or settling specific debts to lower monthly payments. Preparing a new application after improving financial indicators demonstrates stronger repayment capacity. Those who require additional guidance can consult a financial advisor to align their financial profile with the lending criteria used in Malaysia’s banking system.
Legal Notice
The contents of this publication are for reference purposes only and may not be current as at the date of accessing this publication. We do not take responsibility for the accuracy of its contents. They do not constitute legal advice and should not be relied upon as such. Specific legal advice about your specific circumstances should always be sought separately before taking any action based on this publication.