Discover how BNPL services are changing the way Malaysians shop and manage their finances. From easy approval processes to flexible repayment options, this guide will help you understand how BNPL works, its benefits and drawbacks, and practical tips for using it responsibly.
Whether you’re considering BNPL for the first time or looking to refine your usage, this article provides the insights you need to make informed financial decisions.
What is Buy Now, Pay Later (BNPL)?
Buy Now, Pay Later (BNPL) is a growing payment option in Malaysia that allows consumers to purchase goods and services immediately and pay for them in installments over a specified period. BNPL services provide an alternative to traditional credit cards and personal loans, offering more flexibility and often an interest-free repayment structure if paid within the agreed timeframe.
In recent years, BNPL has gained significant traction in Malaysia, especially among young consumers and those seeking to manage their cash flow more effectively.
As BNPL becomes more integrated into the fabric of Malaysia's financial ecosystem, it is essential for consumers to understand how this payment option works and its implications for their financial wellbeing. While BNPL presents a convenient way to spread the cost of purchases, it is crucial for users to be aware of the terms and conditions, including repayment schedules and any associated fees.
How BNPL Works in Malaysia
BNPL services in Malaysia typically work by offering consumers the option to divide their purchase payments into smaller, manageable installments. Here’s how the process generally works:
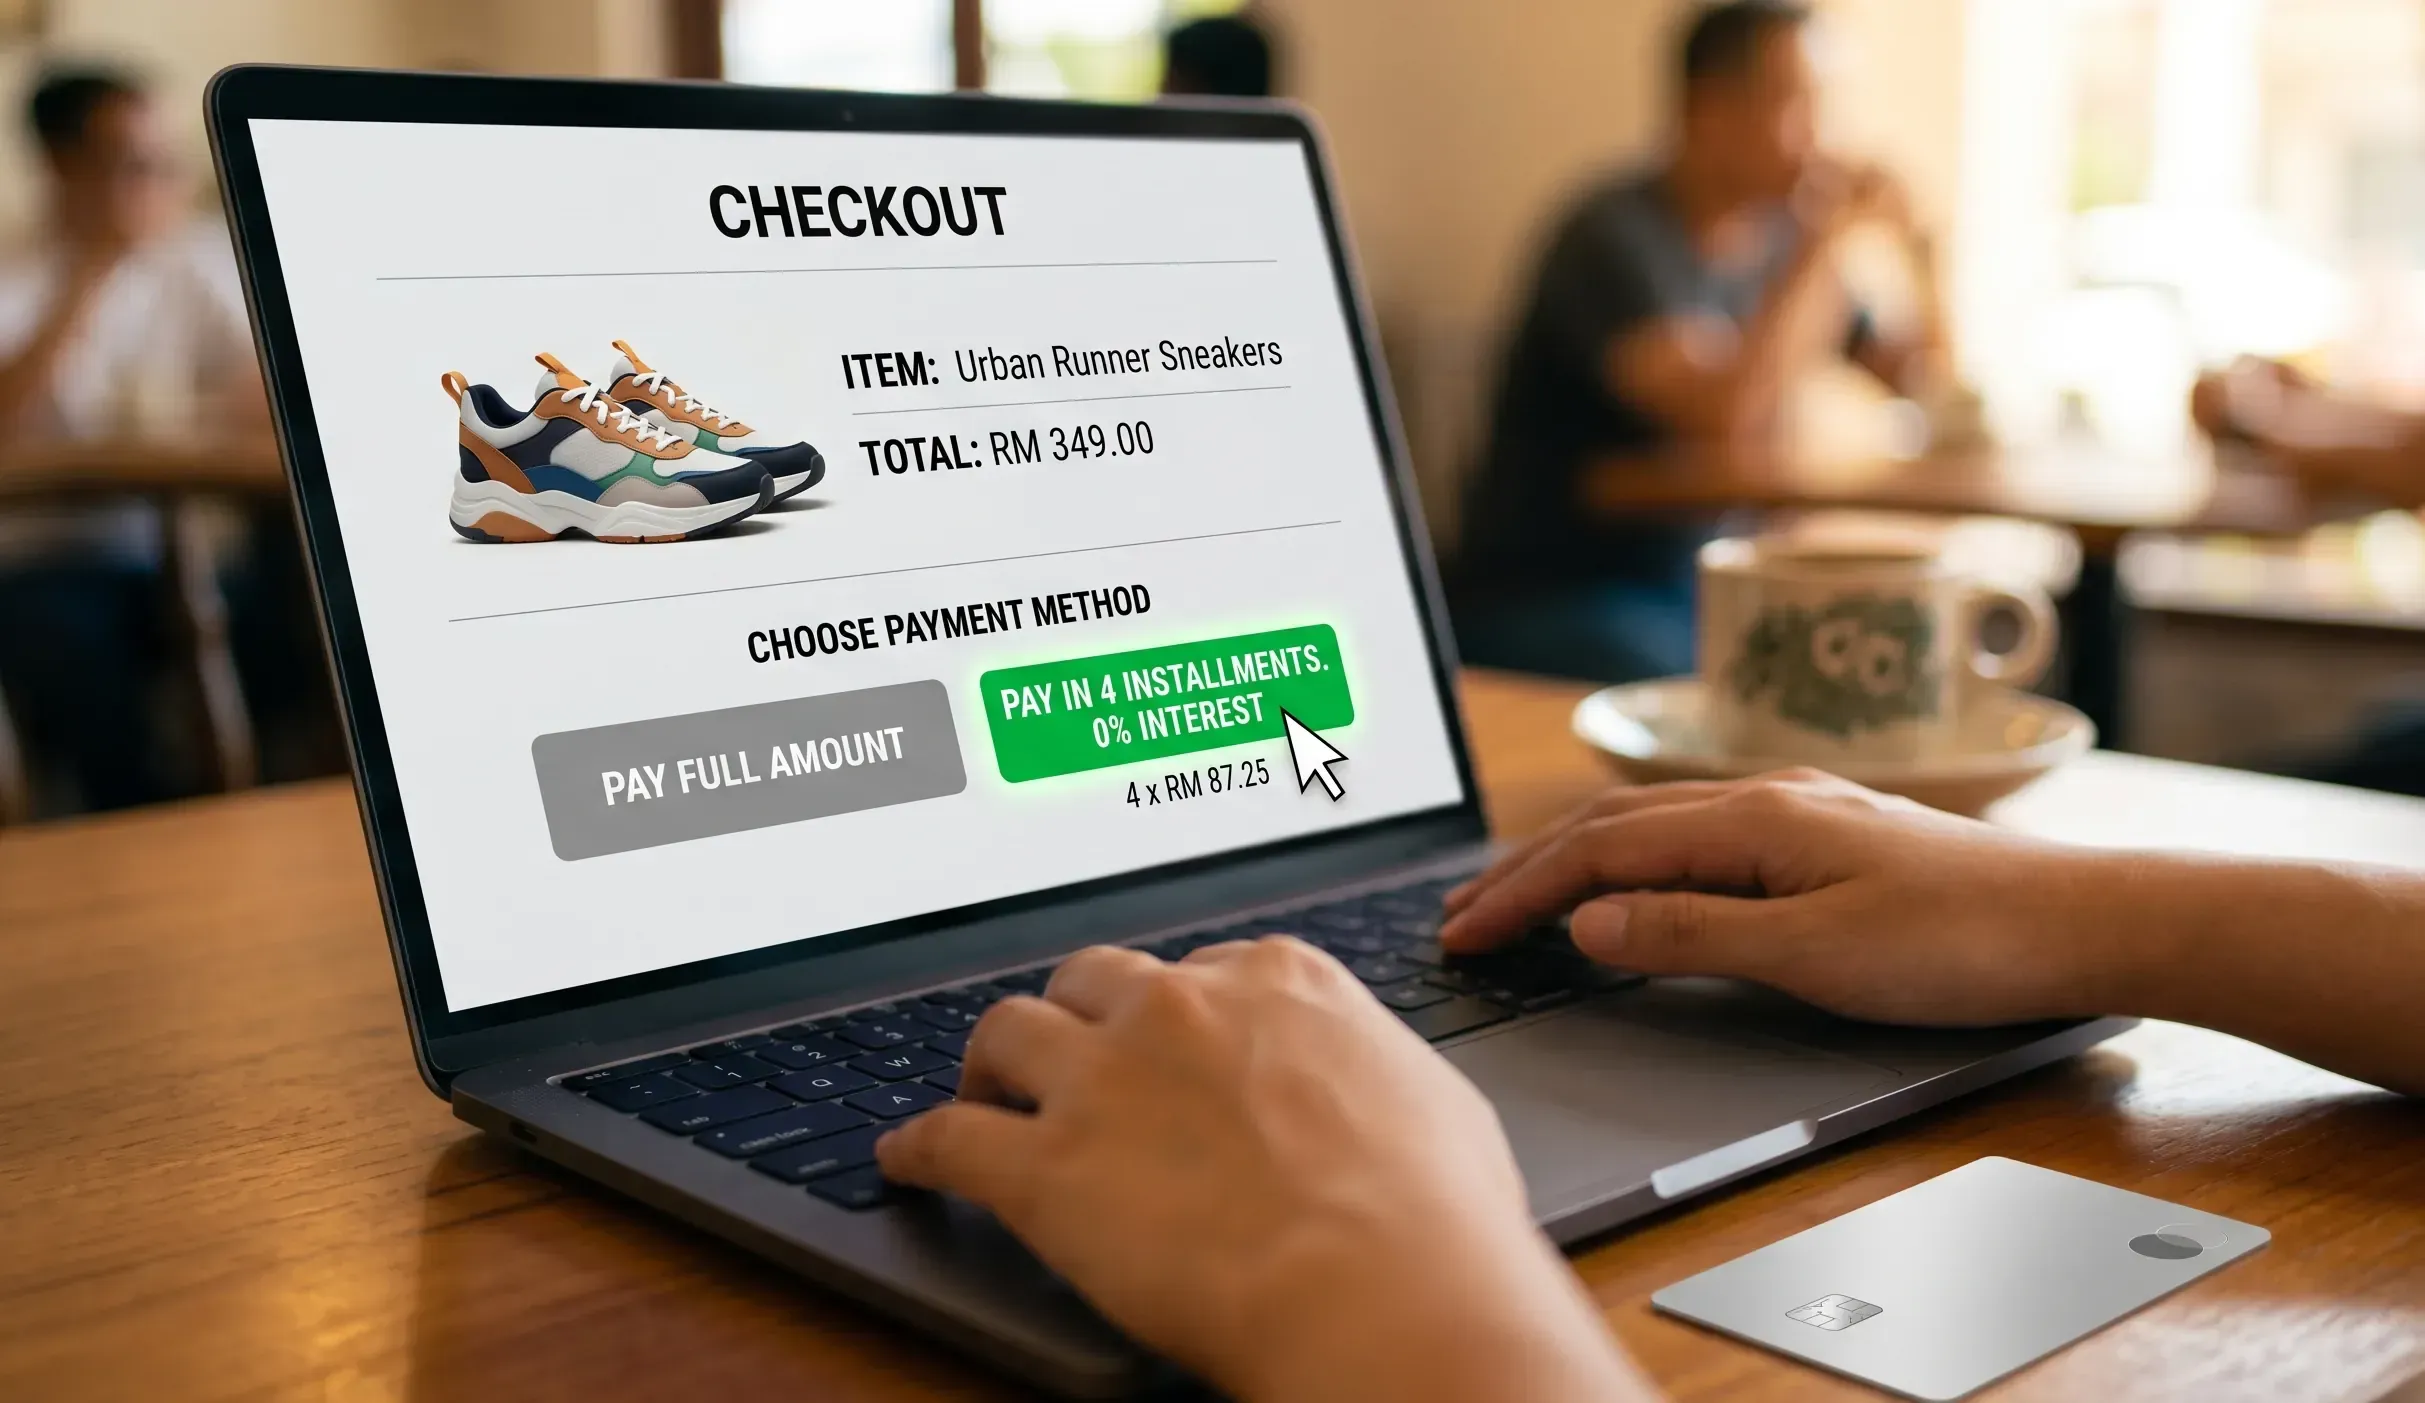
- Selecting BNPL at Checkout: When shopping online or in-store, consumers can choose BNPL as their payment method during checkout. This option is often presented alongside other payment methods like credit cards and online bank transfers.
- Approval Process: Once a consumer selects BNPL, the service provider conducts a quick approval process. This may involve checking the consumer's credit history, payment reliability, and spending behavior. The approval is usually instant, and users can start using the service immediately after confirmation.
- Repayment Terms and Installments: After purchase, consumers typically have a repayment period ranging from 30 days to several months (e.g., 3, 6, or 12 months). The repayment amount is divided into equal installments, which are automatically deducted from the consumer’s bank account or charged to their BNPL account.
- Interest and Fees: Many BNPL services offer interest-free repayment options if payments are made within the specified period. However, late payments may incur interest charges or late fees. Some BNPL providers charge interest from the moment of purchase, which is added to the total amount payable.
- Consumer Protection: Unlike credit cards or personal loans, BNPL services in Malaysia often have fewer consumer protections in place, meaning users must be vigilant about their repayment obligations.
In essence, BNPL offers a flexible, interest-free payment option for consumers who need to spread the cost of purchases over time. However, users should be aware of potential late fees or interest if payments are missed.
Advantages and Disadvantages of BNPL
Buy Now, Pay Later (BNPL) services have become increasingly popular in Malaysia, offering numerous benefits but also presenting certain risks.
Advantages:
- Easy Approval: BNPL services typically offer an easy approval process. Many providers do not require a credit check, which makes them accessible to a broader range of consumers, including those without a credit history or those who may struggle to get traditional credit cards.
- Interest-Free Options: If payments are made within the specified period, many BNPL services offer interest-free options, allowing consumers to avoid extra charges. This makes it a cost-effective option for those who can pay on time.
- Flexibility: BNPL allows consumers to spread out payments over several weeks or months, which can help in managing cash flow, especially for larger purchases. The flexibility of selecting installment terms (e.g., 3 months, 6 months, or 12 months) makes it adaptable to various financial situations.
Disadvantages:
- Potential for Overspending: The ease of using BNPL can sometimes lead to overspending. Consumers may make purchases they cannot afford, believing they will be able to pay later, which could strain their finances if not carefully managed.
- Late Payment Fees: If payments are missed, BNPL providers often charge late payment fees, and in some cases, they may also start charging interest. This can quickly increase the total amount owed, turning an interest-free plan into a costly option.
- Lack of Consumer Protection: BNPL services generally offer less protection than credit cards, which often come with fraud protection and dispute resolution options. If a product is defective or a service is not rendered, consumers may have fewer avenues for recourse.
Before using BNPL, Malaysian consumers should assess their ability to repay on time and understand the terms of service, as these can vary by provider.
Tips Before Using BNPL: Making It Work for You
While BNPL offers convenience, it’s important for consumers to use it responsibly. Here are some practical tips to ensure BNPL works for you:
- Set a Budget: Before opting for BNPL, evaluate your financial situation. Make sure you can comfortably afford the monthly payments. Set a budget to keep track of your expenses and ensure you’re not overextending yourself with too many BNPL purchases.
- Understand the Terms: Always read the fine print of the BNPL agreement. Be aware of repayment terms, fees, and any penalties for late payments. Some providers charge interest if payments are not completed on time, which could lead to unexpected financial strain.
- Plan for Payments: Set up reminders or automate payments to avoid missing deadlines. Missing a payment can result in late fees or interest charges, which can quickly accumulate and undermine the advantages of using BNPL.
- Limit Your Use: Use BNPL sparingly, especially for large purchases. If you find yourself relying too much on BNPL for everyday expenses, it could be a sign that you are overspending or not managing your finances properly.
- Be Mindful of Impulse Buying: BNPL services can encourage impulse buying because of the immediate gratification they provide. Before committing to a BNPL plan, consider whether the purchase is truly necessary and if you can afford it without relying on installment payments.
By using BNPL responsibly and ensuring that payments are manageable, you can enjoy the flexibility it offers while avoiding financial pitfalls. Always weigh the benefits against the potential risks to make an informed decision.
BNPL vs. Traditional Payment Methods: Credit Cards and Personal Loans
When considering financing options, it's essential to understand the differences between Buy Now, Pay Later (BNPL), credit cards, and personal loans. Each has its pros and cons, and the right choice depends on your financial needs.
BNPL vs. Credit Cards:
- Interest Rates: BNPL services often offer interest-free installments if paid on time, while credit cards charge interest on outstanding balances if not paid in full each month. Credit card interest rates in Malaysia can be high, ranging from 15% to 18% per year, making it a more expensive option if payments are not cleared quickly.
- Eligibility: BNPL options tend to have more lenient eligibility requirements, often not requiring a credit check, whereas credit cards typically require a good credit score and income verification.
- Repayment Flexibility: BNPL usually offers fixed repayment terms, with payments due over a set period (e.g., 3, 6, or 12 months). Credit cards offer ongoing revolving credit, which can be used as long as the credit limit is not exceeded. However, credit cards provide more flexibility in repayments as consumers can pay off their balances at their own pace (within the minimum payment requirement).
BNPL vs. Personal Loans:
- Interest Rates: Personal loans typically come with lower interest rates compared to credit cards, especially if you have a good credit score. BNPL can be interest-free if repaid within the agreed period, but may charge higher rates if payments are missed.
- Loan Amount: Personal loans offer larger amounts compared to BNPL, which is typically used for smaller, short-term purchases. Personal loans are also more suitable for significant expenses like home renovations or consolidating debt.
- Approval Process: Personal loans usually involve a more extensive approval process, including a credit check and documentation of income. BNPL, on the other hand, has a much quicker and simpler approval process.
Each payment method has its own advantages depending on your financial situation. BNPL is an excellent option for small, short-term purchases with fixed repayment schedules, while credit cards and personal loans offer more flexibility for larger expenses.
Should You Use BNPL? Is It Right for You?
Whether or not Buy Now, Pay Later (BNPL) is the right choice depends on your financial situation and spending habits. Here are some scenarios to consider:
When BNPL is Beneficial:
- Emergencies: BNPL can be a useful option for unexpected expenses, like urgent repairs or medical bills, as it allows you to spread the cost over time.
- Large Purchases: If you're buying a big-ticket item, such as electronics or furniture, BNPL can help break down the payment into manageable chunks without incurring high-interest rates, as long as you pay on time.
When BNPL May Not Be Ideal:
- Ongoing Expenses: If you're relying on BNPL for regular, everyday purchases, it can quickly lead to overspending and financial strain. It's better to reserve BNPL for one-time purchases or emergencies.
- Debt Management Struggles: If you already have a lot of debt, BNPL may not be the best option. It could lead to accumulating more financial obligations, especially if you struggle with making timely payments.
Before using BNPL, assess your ability to repay on time and consider how it fits within your overall financial strategy. If used responsibly, BNPL can be a helpful tool, but it’s important to avoid overextending yourself and to always stay within your budget.
Common Mistakes to Avoid When Using BNPL
While Buy Now, Pay Later (BNPL) can be a convenient payment method, there are several common mistakes that consumers often make, which can lead to financial difficulties. Here are some pitfalls to avoid:
- Not Tracking Payments: One of the most common mistakes is forgetting to keep track of BNPL payments. Missing deadlines can result in late fees, interest charges, and damage to your credit score. To avoid this, set up reminders or automate your payments to ensure you stay on top of your obligations.
- Overextending Credit: With the ease of BNPL, it's easy to make multiple purchases without realizing how much you're committed to paying back. This can lead to overspending, making it difficult to meet payment deadlines. To prevent this, set a limit on how often you use BNPL and track your total outstanding balance.
- Not Understanding the Terms and Conditions: Consumers often overlook the terms of their BNPL agreements, especially regarding fees, repayment schedules, and penalties for missed payments. Always read the fine print and make sure you understand the repayment terms before committing to any BNPL plan. Be aware of the interest rates that apply if payments are missed or if you extend the repayment period.
- Using BNPL for Non-Essential Purchases: BNPL should be used for planned purchases or emergencies, not for impulse buying. Using BNPL to finance non-essential items can lead to unnecessary debt. Evaluate your purchase carefully and consider whether you can afford to pay for it outright before choosing BNPL.
By avoiding these mistakes, you can use BNPL responsibly and take full advantage of its benefits without risking financial strain.
Key Takeaways and Final Thoughts
In summary, Buy Now, Pay Later (BNPL) offers an attractive, flexible payment option for Malaysian consumers, allowing them to break down larger purchases into manageable installments. However, it’s crucial to understand both the benefits and risks associated with BNPL. While it can be a useful tool for short-term purchases or emergencies, it’s essential to avoid overspending, stay on top of repayments, and fully understand the terms before committing.
Consumers should approach BNPL with caution, using it as a means to manage payments rather than as a quick fix for financial challenges. By using BNPL responsibly, keeping track of payments, and setting limits, you can avoid potential pitfalls and maintain healthy financial habits.
Legal Notice
The contents of this publication are for reference purposes only and may not be current as at the date of accessing this publication. We do not take responsibility for the accuracy of its contents. They do not constitute legal advice and should not be relied upon as such. Specific legal advice about your specific circumstances should always be sought separately before taking any action based on this publication.